


| HEADLINE |
|

How Much Worse Can It Get?
IMF Summit Confronts Triple Threat of War, Debt and Energy Shock
Published : Monday, 12 October, 2026 at 12:00 AM
Faruk Ahmed


 What happens when war chokes energy supplies, debt devours government revenues and food prices threaten millions of already struggling households?
The stakes are enormous. The US-Israeli-led war with Iran and Russia's continuing war against Ukraine have exposed the fragility of global supply chains, sent shockwaves through energy markets and heightened fears of another inflationary spiral. For developing countries, the danger is particularly acute: more expensive fuel, costly borrowing, capital flight and dwindling fiscal space threaten to turn external shocks into domestic economic crises.
The question facing policymakers is no longer simply how to sustain growth. It is how to prevent war-driven disruptions from triggering a vicious cycle of inflation, higher interest rates, debt distress and painful austerity.
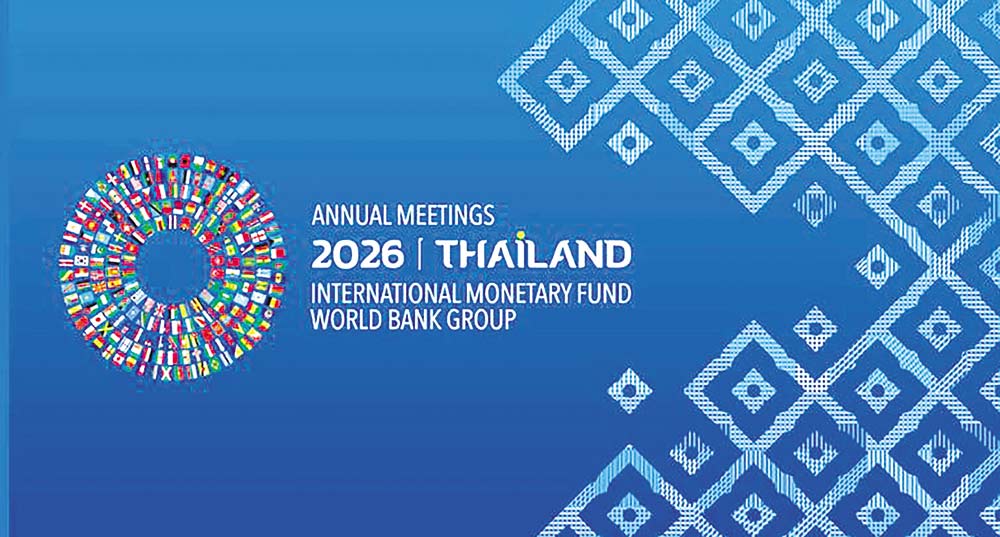
Bangkok's Queen Sirikit National Convention Center will host more than 15,000 delegates from 191 countries, including finance ministers, central bank governors, business leaders and civil society representatives. The return of the meetings to Bangkok after 35 years lends historical significance to the gathering, but the economic circumstances could hardly be more unsettling.
IMF Managing Director Kristalina Georgieva has delivered a stark warning: “Winter is coming.”
Energy Shock Threatens To Reignite Inflation
The disruption of shipping through the Strait of Hormuz has laid bare the vulnerability of global energy supplies. The strategic waterway normally carries around one-fifth of the world's oil, making prolonged disruption a direct threat to transport, manufacturing, electricity generation and food production.
Emergency oil releases may offer temporary relief, but they cannot indefinitely offset a sustained supply shock. Higher diesel prices raise transport costs; expensive fertiliser threatens agricultural production; and rising food prices squeeze household incomes while complicating central banks' efforts to contain inflation.
For oil-importing economies, the consequences extend beyond higher fuel bills. Foreign-exchange reserves come under pressure, currencies weaken and current-account deficits can widen. Governments face the uncomfortable choice of absorbing higher costs through subsidies or passing them on to consumers already struggling with the cost of living.
The danger lies in the interaction of these pressures. An energy shock can become a food crisis, a currency crisis and, ultimately, a debt crisis. A potentially severe El Niño weather pattern could compound the damage by disrupting harvests and intensifying extreme heat.
Debt Threatens To Overwhelm Developing Economies
Behind the immediate energy emergency lies a more enduring threat: the accumulation of public debt. The IMF warns that global public debt is on course to exceed 100 per cent of gross domestic product by 2030, reaching levels not seen since the aftermath of the Second World War.
Yet the burden is far from evenly distributed. Wealthier economies generally have deeper financial markets and greater borrowing capacity. Poorer countries often face higher interest rates, narrower tax bases and limited foreign-exchange buffers, leaving them more exposed to changes in global financial conditions.
The consequences are already severe. Interest payments absorb more than 10 per cent of government revenue in developing countries on average, according to figures cited in the debt debate. Every additional taka, dollar or pound spent servicing debt leaves less available for hospitals, education, infrastructure, job creation and climate resilience.
The international response remains uncertain. The temporary debt-service suspension introduced by G20 leaders during the Covid-19 crisis has little apparent prospect of being replicated on a comparable scale. Domestic political pressures and governments' own financial constraints have narrowed the appetite for another coordinated initiative.
Without more effective debt-restructuring mechanisms, vulnerable economies risk being trapped in a cycle of borrowing at higher rates simply to meet existing obligations.
Will IMF Reforms Rescue Economies Or Deepen Austerity?
The Bangkok meetings will also test the credibility of the international financial safety net. Developing countries are concerned about proposals for fewer but deeper reforms under IMF lending programmes, fearing that tougher conditions could force further spending cuts and tax increases when living costs are already high.
The dilemma is real. Weak governance, unsustainable budgets and structural distortions cannot be ignored indefinitely. But reforms that place excessive burdens on households, undermine essential public services or suppress productive investment may weaken the very economic recovery they are intended to secure.
Kenya's experience offers a cautionary lesson: fiscal measures intended to address financial pressures have provoked significant public protests. Economic adjustment without credible safeguards for vulnerable groups can quickly become a political crisis.
The IMF therefore faces a critical test. Can it enforce fiscal discipline while allowing countries enough room to protect essential services, support employment and invest in future growth? Or will increasingly stringent conditions deepen hardship and erode public confidence in the institutions designed to prevent financial collapse?
For Bangladesh, represented by a delegation led by Finance Minister Amir Khosru Mahmud Chowdhury, the debate has immediate implications. Dhaka is expected to discuss a proposed $4.5 billion lending programme with the IMF on the sidelines of the meetings.
The Price of Global Inaction
The absence of US Treasury Secretary Scott Bessent adds uncertainty to an already difficult gathering, although senior US officials are expected to represent Washington. More broadly, geopolitical tensions are making international economic coordination increasingly difficult precisely when it is most needed.
Loading...
Loading...
Also read


Editor : Iqbal Sobhan Chowdhury
Published by the Editor on behalf of the Observer Ltd. from Globe Printers, 24/A, New Eskaton Road, Ramna, Dhaka.
Editorial, News and Commercial Offices : Aziz Bhaban (2nd floor), 93, Motijheel C/A, Dhaka-1000.
Phone: PABX- 41053001-06; Advertisement: 41053012; 01793317829, 01550707291, E-mail: [email protected], [email protected] Online: email: [email protected] 41053014; 01550707297 Advertisement: 01550707296


