


| HEADLINE |
|

BD sees modest rise in digital payments as cash STILL largely dominates
Published : Monday, 2 November, 2026 at 12:00 AM
Mizanur Rahman


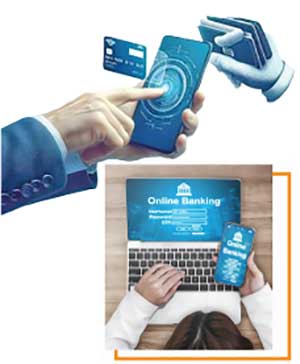 Digital transactions in Bangladesh are increasing, but the country remains heavily dependent on cash, cheques and over-the-counter payments, highlighting the challenges of building a less-cash economy despite the expansion of mobile financial services, internet banking and QR-based payments.
According to the Bangladesh Payment Systems Report 2024 published by Bangladesh Bank, the number of digital transactions rose from 36.67 crore in December 2023 to 40.31 crore in December 2024, an increase of around 10 per cent. However, digital payments' share of total transactions declined from 51 per cent to 47 per cent during the period.
The total value of digital transactions increased modestly from Tk 75,140 crore to Tk 76,340 crore. Yet their share of the overall transaction value fell from 29 per cent to 28 per cent, indicating that traditional payment methods continued to dominate in terms of money exchanged.
The figures highlight a key contradiction in Bangladesh's digital finance landscape: more people are using electronic channels, but the growth has not been sufficient to reduce the economy's reliance on physical money.
Non-digital transaction volumes surged 31.4 per cent, from 34.62 crore in December 2023 to 45.49 crore in December 2024. Their share of total transaction value also increased from 71 per cent to 72 per cent.
The trend suggests that while digital platforms are widely used for small, frequent payments, cash, cheques and over-the-counter services remain important for many transactions, particularly those involving larger amounts.
Mobile financial services (MFS) remain a major pillar of Bangladesh's digital finance ecosystem. However, Bangladesh Bank's report points to a shift towards cash-based behaviour within the sector.
The share of MFS-based digital transactions by volume fell from 46.82 per cent to 40.99 per cent between December 2023 and December 2024. Their share by value also edged down from 2.37 per cent to 2.36 per cent.
The figures indicate that, although mobile wallets provide convenient access to financial services, many users continue to withdraw money rather than use it directly for digital purchases and payments.
This limits the potential of MFS to reduce cash dependency. Greater merchant acceptance, easier payments and stronger incentives for digital transactions will be necessary to encourage consumers to keep money within the electronic payment ecosystem. Despite the broader challenges, some digital payment channels are recording encouraging growth.
Bangla QR, the country's standardised QR-based payment system, recorded a 104 per cent increase in transaction volume and a 69 per cent rise in transaction value, according to the information provided in the Bangladesh Bank report. The system is designed to make digital payments more accessible to businesses and consumers.
Internet Banking Fund Transfer (IBFT) also emerged as a dominant channel under the National Payment Switch Bangladesh (NPSB), accounting for 80 per cent of the system's transaction value in 2024. The NPSB supports transactions across participating banks and payment channels, including fund transfers, cards and QR payments.
Bangladesh Bank has also taken regulatory steps to strengthen the payment ecosystem. These include the Payment and Settlement System Act, 2024, and the introduction of TakaPay, the country's domestic card scheme, launched to support a more accessible and cost-effective payment infrastructure.
However, expanding the availability of digital services alone will not guarantee widespread adoption. Small merchants may be reluctant to accept electronic payments if transaction charges, settlement delays or technological requirements make them less attractive than cash.
A research paper by Bangladesh Bank officials, titled QR-Based Payment Systems in Bangladesh: A Comprehensive Overview of Developments and Adoption Barriers, identifies limited merchant adoption, low user awareness, trust concerns and transaction costs as important obstacles to wider QR payment adoption. Economists and financial-sector specialists have called for stronger policy support to accelerate Bangladesh's transition towards a less-cash economy.
Debapriya Bhattacharya, distinguished fellow at the Centre for Policy Dialogue (CPD), highlighted the potential benefits of a cashless economy, including greater efficiency, financial inclusion, lower transaction costs and improved economic formalisation, at the Cashless Bangladesh Summit 2025.
Ashikur Rahman, principal economist at the Policy Research Institute of Bangladesh (PRI), also called for a clear and coordinated roadmap to expand digital payments, according to a report published in January 2026. The discussion highlighted the continued dominance of cash and the limited use of QR payments in Bangladesh.
Their concerns underline the need to go beyond expanding digital infrastructure. Moving government payments, institutional transactions and merchant purchases onto electronic platforms could help create more consistent demand for digital services.
At the same time, consumer confidence remains critical. Fraud involving fake links, stolen one-time passwords, account takeovers and impersonation can discourage people from using digital payment platforms. Effective complaint resolution, stronger authentication, cybersecurity safeguards and public awareness campaigns are therefore essential.
For Bangladesh, the objective should not simply be to increase the number of digital transactions but to make electronic payments a practical alternative to cash in everyday economic activity.
The challenge is to build a system that is affordable for small businesses, convenient for consumers, interoperable across financial institutions and secure enough to earn public trust. Without these changes, digital payments may continue to grow in absolute numbers while cash retains its dominant position in the economy.
Loading...
Loading...
Also read


Editor : Iqbal Sobhan Chowdhury
Published by the Editor on behalf of the Observer Ltd. from Globe Printers, 24/A, New Eskaton Road, Ramna, Dhaka.
Editorial, News and Commercial Offices : Aziz Bhaban (2nd floor), 93, Motijheel C/A, Dhaka-1000.
Phone: PABX- 41053001-06; Advertisement: 41053012; 01793317829, 01550707291, 01550707296
E-mail: [email protected], [email protected]. [email protected], [email protected], [email protected], [email protected], Online-email: [email protected]
Published by the Editor on behalf of the Observer Ltd. from Globe Printers, 24/A, New Eskaton Road, Ramna, Dhaka.
Editorial, News and Commercial Offices : Aziz Bhaban (2nd floor), 93, Motijheel C/A, Dhaka-1000.
Phone: PABX- 41053001-06; Advertisement: 41053012; 01793317829, 01550707291, 01550707296
E-mail: [email protected], [email protected]. [email protected], [email protected], [email protected], [email protected], Online-email: [email protected]


