


| HEADLINE |
|

Protect Depositors, Not Bank Profits: Salim Rahman
Published : Wednesday, 18 November, 2026 at 12:00 AM
Interviewer: Shamsul Huda


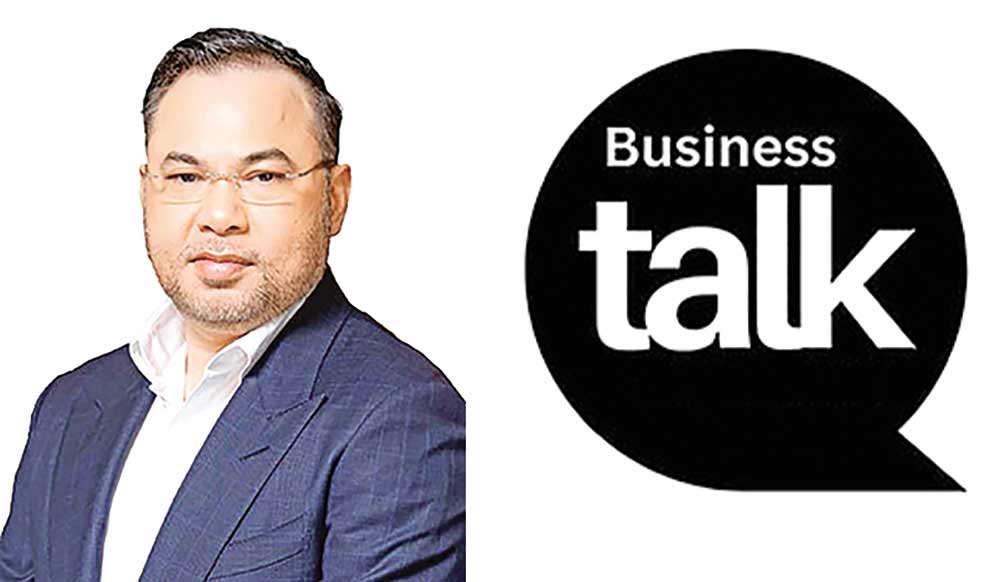 Bangladesh's banking sector cannot afford aggressive lending at the cost of depositors' money, as weak governance, mounting bad loans and sluggish private-sector credit continue to undermine financial stability and economic growth, says Alhajj Salim Rahman, Chairman of the Executive Committee of Al-Arafah Islami Bank PLC.
Warning against reckless credit expansion amid widespread financial weaknesses, he says banks must prioritise deposit protection, responsible lending and actual loan recovery over short-term profits, even as sufficient liquidity remains trapped in the banking system and businesses struggle to obtain financing.
"Even some third- and fourth-generation banks are also struggling with serious financial weaknesses following substantial withdrawals and losses of funds," Rahman told The Daily Observer in an exclusive interview.
He believes restoring confidence in the banking industry will require time, effective supervision and far-reaching institutional reforms rather than quick fixes.
"I am optimistic about recovery through patience, discipline and proper management. I do not, however, expect an immediate turnaround," he said.
The recovery process could take a year or longer, depending on how effectively banks address their weaknesses, improve governance and restore financial discipline. Nevertheless, he sees no reason to lose confidence in the industry's long-term prospects.
One of the most pressing concerns, according to Rahman, is the sluggish growth of private-sector credit despite sufficient liquidity in the banking system. The slowdown is constraining business expansion, investment and employment, adding to pressure on an economy already grappling with global uncertainty, rising energy costs and a difficult business environment.
However, he considers banks' cautious lending approach justified, arguing that financial institutions must remember that the money they lend belongs primarily to depositors.
"The first responsibility of banks is to protect depositors' money. Lending simply to increase business volume can eventually put the entire institution at risk," he observed.
He places greater emphasis on the quality of lending than on the volume of credit, warning that inadequate borrower assessments, unrealistic business projections and excessive exposure can eventually swell non-performing loans and weaken banks' financial positions.
Proper due diligence, realistic cash-flow assessments, regular monitoring and borrowers' repayment capacity must therefore guide every lending decision, he said.
Rahman also expressed concern over the slow disbursement of the government's Tk60,000 crore stimulus and refinancing package, saying the availability of funds alone cannot revive distressed businesses.
Many factories have shut down, while numerous entrepreneurs are struggling with financial and operational difficulties. However, not every distressed enterprise has the capacity to resume production or repay fresh loans.
Banks must therefore distinguish between genuine entrepreneurs with viable businesses and borrowers whose operations have become commercially unsustainable, he said.
He favours financing businesses with established markets, regular customers, realistic sales prospects and sufficient cash flow to meet repayment obligations. Before extending fresh credit, banks must assess market demand, customer orders, production capacity and the prospects of restarting operations.
"Providing additional funds without proper assessment may increase non-performing loans instead of supporting economic recovery," is the central concern behind his cautious approach.
He does not support restricting credit to genuine entrepreneurs merely because the banking sector is facing difficulties. Viable businesses deserve financial support because their recovery can protect jobs, sustain industrial production and stimulate wider economic activity.
But extending fresh loans to businesses without sustainable cash flows would only postpone their problems and expose banks to further losses. He therefore advocates selective financing based on commercial viability rather than indiscriminate credit expansion.
On banks' growing investments in government securities, Rahman said such investments should not automatically be interpreted as evidence of excessive profitability or reluctance to finance businesses.
When private-sector credit demand remains weak and viable lending opportunities are limited, government securities provide banks with a relatively secure avenue for deploying excess liquidity.
Although their returns are not particularly attractive, such investments help banks manage available funds while meeting their obligations to depositors. He considers this a practical liquidity-management decision rather than a substitute for productive private-sector lending.
At Al-Arafah Islami Bank, the immediate strategy is to protect liquidity, support financially sound customers and intensify loan recovery.
Rahman considers liquidity protection more important than short-term profitability during periods of uncertainty, arguing that a bank must remain capable of meeting its obligations at all times.
The bank is focusing on existing customers with sound businesses and satisfactory financial prospects to maintain asset quality and support productive economic activities. At the same time, it is placing greater emphasis on recovering outstanding loans.
He believes actual loan recovery, rather than repeated rescheduling, is essential to restoring financial discipline in the banking industry.
"Rescheduling without meaningful repayment only postpones the problem," he observed, stressing that borrowers must fulfil their obligations while banks strengthen monitoring, enforcement and recovery mechanisms.
He also places good governance, regulatory compliance and institutional accountability at the centre of his long-term vision for Al-Arafah Islami Bank.
Effective governance must begin with a responsible and capable board, which provides the foundation for professional management, transparent decision-making and strong internal controls. Without these safeguards, no bank can achieve lasting financial stability, he said.
Rahman sees substantial potential for Islamic banking in Bangladesh, but says its future depends largely on public confidence and the institutions' ability to demonstrate genuine commitment to Shariah principles.
Transparency, accountability, ethical financing and responsible investment must remain at the heart of Islamic banking operations. Religious identity alone cannot guarantee institutional credibility or financial success, he cautioned.
Islamic banks must combine genuine Shariah compliance with professional management, sound financial practices, improved service quality and strong protection of customers' interests.
Despite the industry's current difficulties, Rahman remains optimistic about its recovery. He acknowledges that domestic weaknesses and global economic uncertainties will continue to weigh on banking operations, but believes gradual improvement is possible through institutional reforms, prudent lending and stronger accountability.
He favours sustainable recovery over unrealistic expectations, placing depositors' interests above aggressive business expansion while recognising the need to finance genuine entrepreneurs and productive industries.
For Rahman, the way forward is clear: stronger governance, responsible lending, effective loan recovery and authentic Shariah compliance must form the foundation of a resilient banking industry.
Only by restoring financial discipline and public confidence, he believes, can Bangladesh's banks regain their strength and make a meaningful contribution to investment, employment and sustainable economic growth.
Loading...
Loading...
Also read


Editor : Iqbal Sobhan Chowdhury
Published by the Editor on behalf of the Observer Ltd. from Globe Printers, 24/A, New Eskaton Road, Ramna, Dhaka.
Editorial, News and Commercial Offices : Aziz Bhaban (2nd floor), 93, Motijheel C/A, Dhaka-1000.
Phone: PABX- 41053001-06; Advertisement: 41053012; 01793317829, 01550707291, 01550707296
E-mail: [email protected], [email protected]. [email protected], [email protected], [email protected], [email protected], Online-email: [email protected]
Published by the Editor on behalf of the Observer Ltd. from Globe Printers, 24/A, New Eskaton Road, Ramna, Dhaka.
Editorial, News and Commercial Offices : Aziz Bhaban (2nd floor), 93, Motijheel C/A, Dhaka-1000.
Phone: PABX- 41053001-06; Advertisement: 41053012; 01793317829, 01550707291, 01550707296
E-mail: [email protected], [email protected]. [email protected], [email protected], [email protected], [email protected], Online-email: [email protected]


