


| HEADLINE |
|

High loan interest puts Dhaka flat market under pressure
Published : Friday, 2 October, 2026 at 12:00 AM
Staff Correspondent


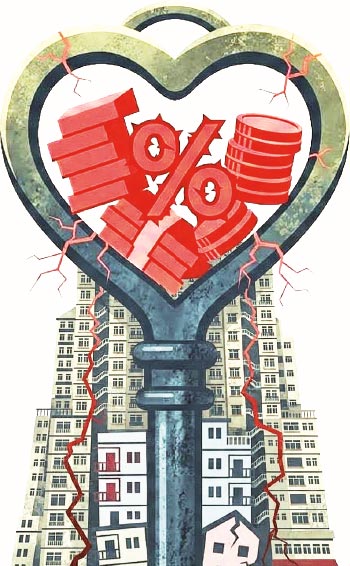 Dhaka’s housing market is facing a growing gap between flat prices and the purchasing power of middle-class buyers. While rising land and construction costs are pushing up flat prices, the high cost of bank loans is making home ownership harder for many families.
For many middle-class families, a housing loan is an important part of buying a flat. But when interest rates remain high, monthly instalments rise. As a result, many potential buyers are delaying their decisions or looking for smaller and cheaper flats.
According to Bangladesh Bank data, the average lending rate of banks stood at 11.96 per cent at the end of April 2026, compared with 12.03 per cent at the end of December 2025.
Although the rate has fallen slightly, borrowing costs remain high enough to put considerable pressure on a middle-class family taking a large, long-term housing loan.
Housing loan rates vary from one bank to another. The effective rate depends on the type of loan, the customer’s risk profile, relationship with the bank and market conditions.
Many housing loans also have variable interest rates. This means the cost of borrowing can change when market conditions change, creating additional uncertainty for long-term borrowers.
The impact becomes clearer when the numbers are calculated. Suppose a buyer needs a Tk50 lakh housing loan to buy a flat in Dhaka. If the loan is taken for 20 years at 12 per cent interest, the monthly instalment would be around Tk55,000.
At 13 per cent interest, the monthly payment would rise to around Tk58,600. At 14 per cent, it could reach about Tk62,200.
A difference of only a few percentage points can therefore increase the monthly payment by several thousand taka. Over 20 years, the difference becomes much larger.
For a Tk50 lakh loan over 20 years, the total interest payment could be around Tk82 lakh at 12 per cent interest. At 14 per cent, it could reach nearly Tk99 lakh.
These calculations do not include the flat price, down payment, registration costs or other expenses. In reality, the total cost of home ownership would be higher.
This shows that the cost of a flat is not limited to its purchase price. Interest on a long-term housing loan can add a significant amount to the actual cost.
For a middle-class family in Dhaka, three calculations are particularly important before buying a flat: how much can be paid as a down payment, how much needs to be borrowed and how much can be paid every month.
But a family’s monthly budget also has to cover children’s education, healthcare, transport, food and other household expenses. So, the amount a bank is willing to lend may not be the amount a buyer feels comfortable borrowing.
This is creating a gap between potential buyers and actual buyers in the housing market.
Many families may want to buy a flat but postpone the decision after calculating the monthly instalment. Some may choose a smaller flat, while others may look for properties farther from central Dhaka. Some may also turn to older or resale flats as relatively affordable options.
At the same time, developers are facing rising costs. Land prices, construction materials, labour, utilities and other expenses all affect the final price of a flat. This makes it difficult for developers to reduce prices sharply.
The market is therefore facing a difficult situation. Developers want to maintain prices because of high construction and production costs, while buyers are waiting because of high prices and expensive loans.
As a result, flats may remain available in the market without enough buyers being able or willing to purchase them.
But lower interest rates alone may not be enough to revive the housing market.
A buyer’s decision also depends on the price of the flat, down payment, income, job security, living costs and expectations about the future economy.
Bangladesh Bank introduced a market-based system for determining bank loan interest rates in its 2024 guidelines. Lending rates are therefore also linked to market factors such as the relationship between banks and customers and the demand and supply of loans.
A slowdown in flat sales can affect more than developers. The impact can spread across the wider supply chain, including rod, cement, tiles, sanitary products, wood, aluminium, furniture, transport and construction workers.
Housing loans are also directly linked to the real estate market. If buyers cannot obtain or afford loans, flat sales can slow. If sales remain slow, developers may become more cautious about starting new projects.
This makes housing loan interest more than a banking issue. It can influence demand across the entire real estate sector. During periods of high interest rates, some buyers may move from larger flats to smaller units. Others may look beyond central Dhaka for more affordable homes.
In the end, the size of the housing market depends not simply on how many people want to buy flats, but on how many can actually afford the monthly cost of owning one.
Loading...
Loading...
Also read


Editor : Iqbal Sobhan Chowdhury
Published by the Editor on behalf of the Observer Ltd. from Globe Printers, 24/A, New Eskaton Road, Ramna, Dhaka.
Editorial, News and Commercial Offices : Aziz Bhaban (2nd floor), 93, Motijheel C/A, Dhaka-1000.
Phone: PABX- 41053001-06; Advertisement: 41053012; 01793317829, 01550707291, E-mail: [email protected], [email protected] Online: email: [email protected] 41053014; 01550707297 Advertisement: 01550707296


